
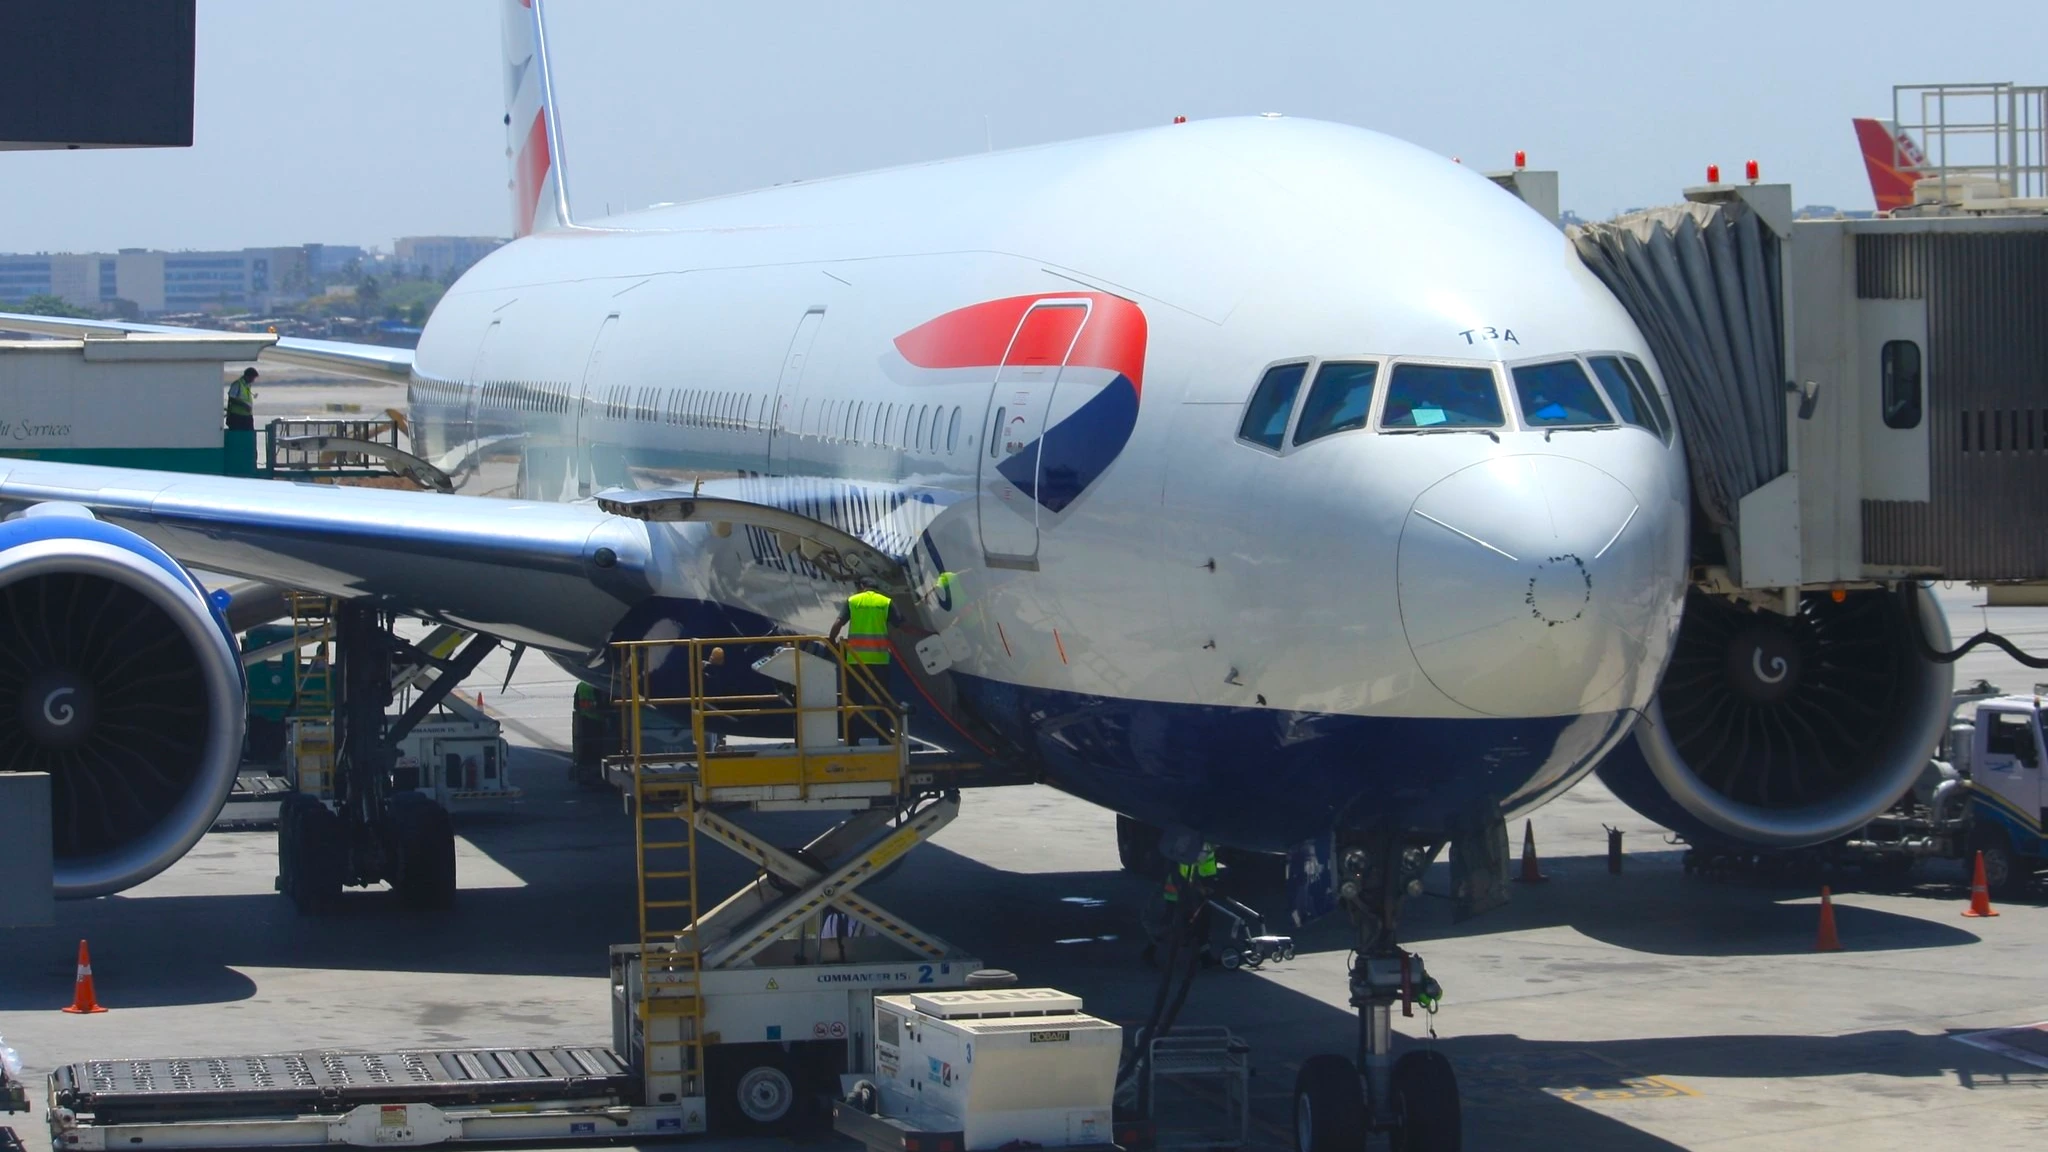
LONDON— British Airways (BA) has won a £5.78 million tax dispute with HM Revenue & Customs (HMRC) over hotel accommodation provided to cabin crew at London Heathrow Airport (LHR) during back-to-back transatlantic rotations.
The Upper Tribunal ruled that the accommodation represented a necessary travel expense rather than a taxable employee benefit, ending HMRC’s appeal against an earlier decision in the airline’s favor.
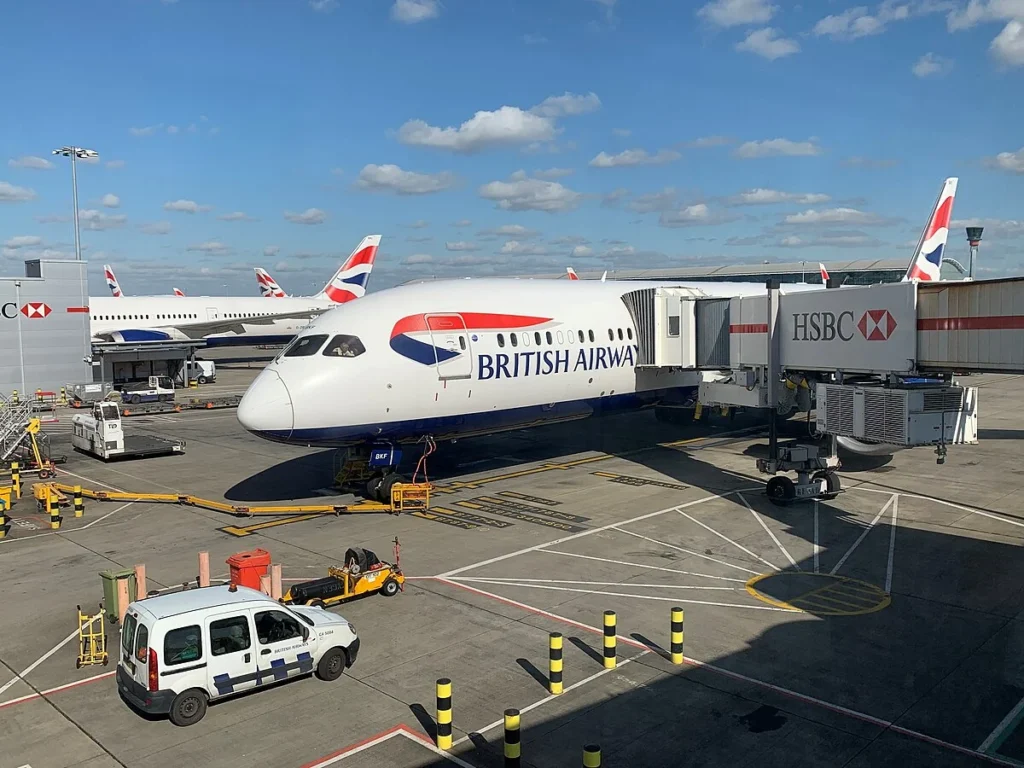
British Airways provides the accommodation to crew members operating certain back-to-back rotations through London Heathrow, where staff may return to the UK before beginning another long-haul sector.
The case concerned whether the cost should generate income tax and National Insurance contributions or remain a business expense connected to the employees’ duties.
British Airways Wins Tax Appeal
The dispute arose from the way BA scheduled cabin crew on back-to-back rotations.
Under these arrangements, crew can complete one transatlantic sector, return to Heathrow, take a mandatory rest period and then operate another flight before their rotation officially ends.
HMRC argued that the hotel accommodation should be treated as part of the crew’s taxable earnings.
The tax authority’s position would have resulted in approximately £5.78 million in income tax and National Insurance liabilities across the period covered by the dispute.
BA maintained that the accommodation was required so crew could comply with aviation safety requirements and continue performing their duties.
The First-tier Tribunal sided with the airline in a decision released on April 3, 2025, prompting HMRC to take the case to the Upper Tribunal.

Tribunal Assesses Crew Rest Rules
The legal dispute also centered on aviation safety rules introduced in 2016. Those rules placed stricter requirements on crew rest during certain back-to-back operations, meaning accommodation at Heathrow could form part of the operational requirements of a flight rotation.
The Upper Tribunal considered whether the hotel stay represented a personal benefit or an expense necessarily incurred while the employees travelled in the performance of their duties.
The judges concluded that the accommodation fell within the latter category.
The tribunal therefore rejected HMRC’s appeal and upheld the principle that the accommodation costs could be treated as deductible travel expenses.
The ruling means the hotel provision does not become taxable employee earnings in the circumstances examined by the court.
Heathrow Accommodation Ruling
The September 28, 2026, judgment provides a significant clarification for British Airways and employers whose workers must travel or remain away from home because of operational or regulatory requirements.
The decision focused on the specific facts of BA’s crew rotations rather than creating a blanket exemption for all employer-provided accommodation, Loyalty Lobby flagged.
For BA, the ruling removes the immediate tax and National Insurance exposure that HMRC had pursued over the Heathrow accommodation.
It also confirms that mandatory rest arrangements can be treated differently from accommodation provided primarily for an employee’s personal convenience.
The case highlights the unusual relationship between aviation scheduling and employment taxation.
For cabin crew operating long-haul rotations, a hotel stay between duties can be an essential part of completing the legally compliant journey rather than a separate personal benefit.
Stay tuned with us. Further, follow us on social media for the latest updates.
Join us on Telegram Group for the Latest Aviation Updates. Subsequently, follow us on Google News
