
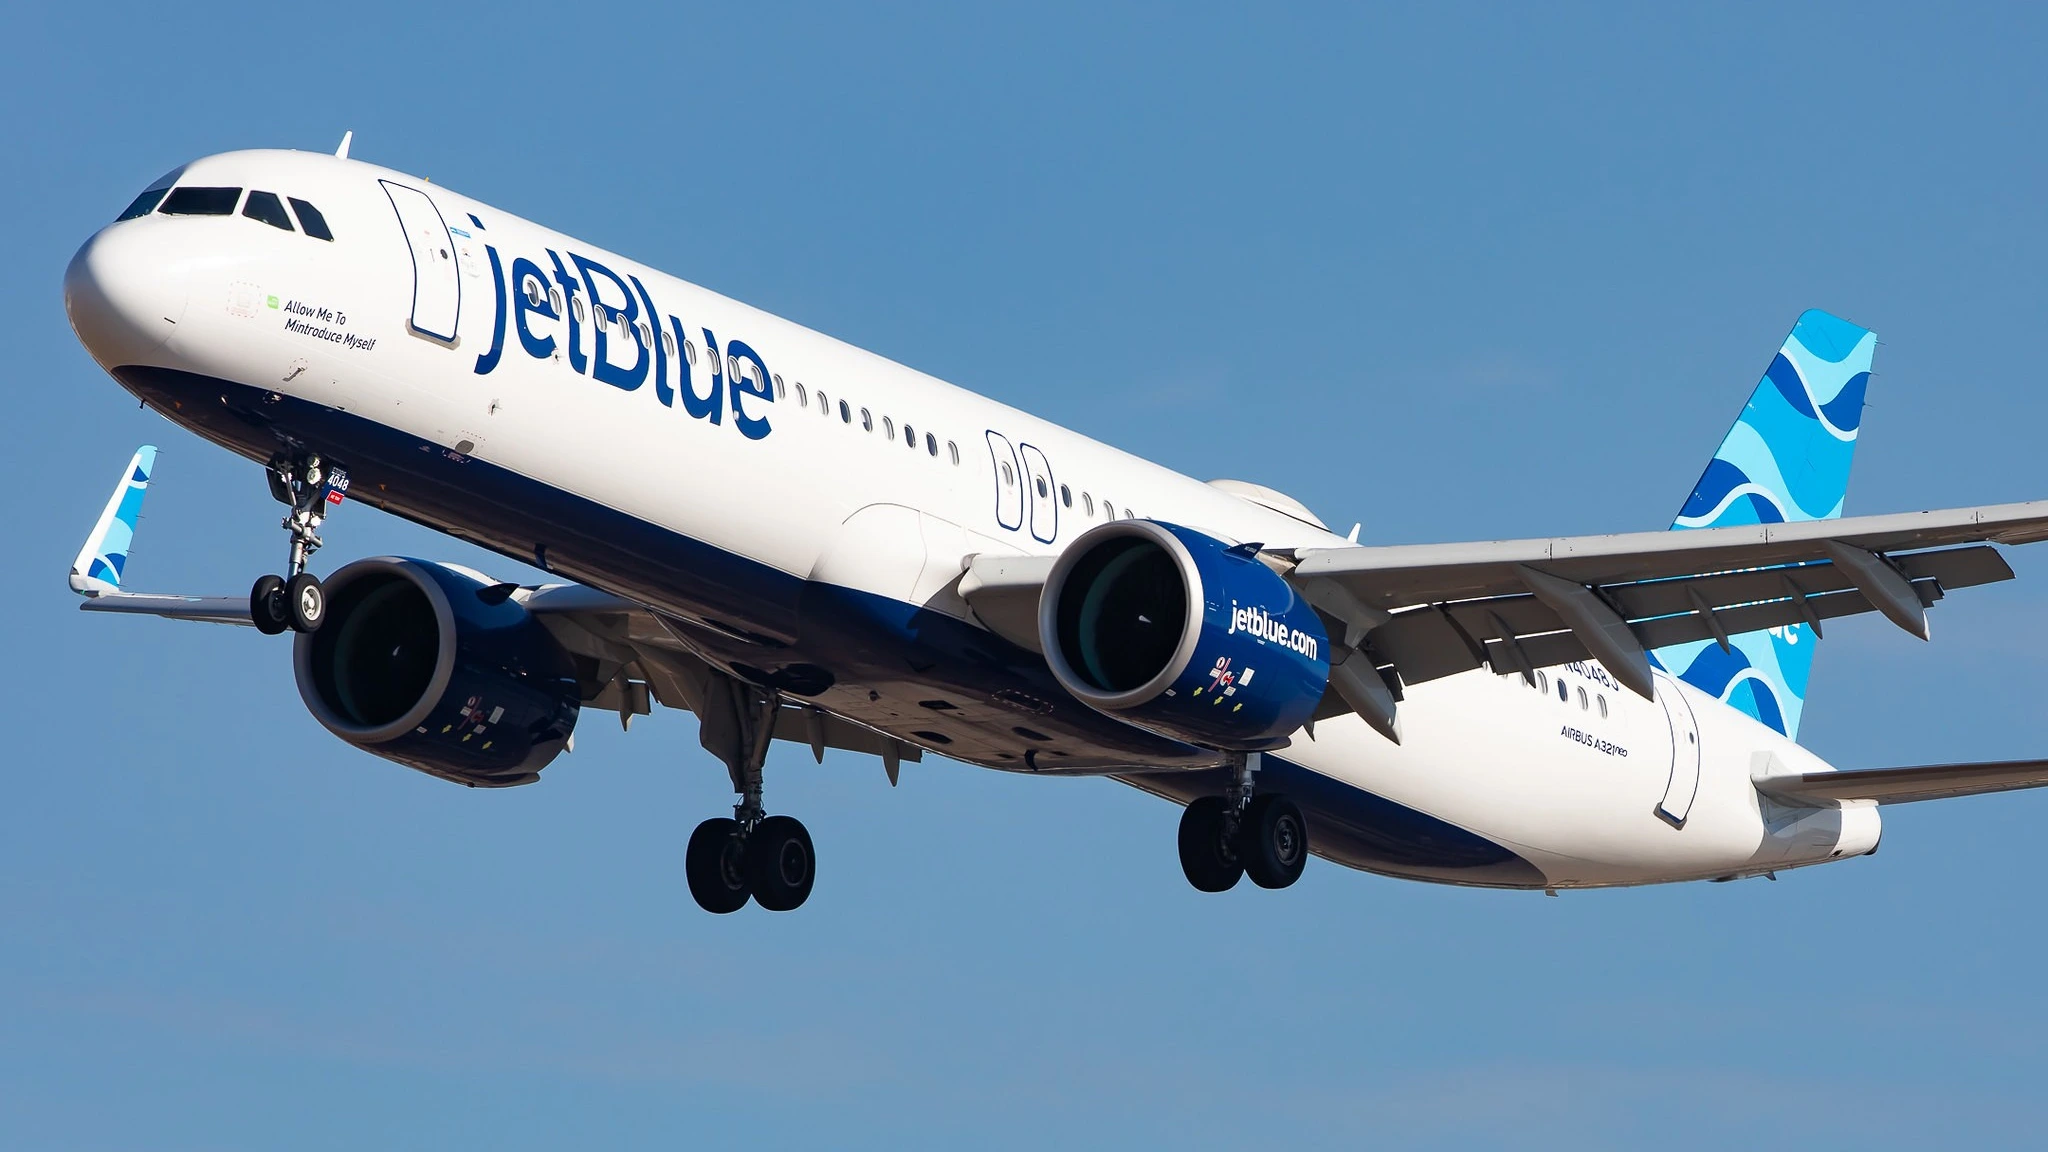
CHICAGO- JetBlue Airways (B6) shares closed at $2.91 on Tuesday, renewing questions about whether the struggling US airline can complete its turnaround without seeking bankruptcy protection or a financial rescue. United Airlines CEO Scott Kirby faced questions about a potential acquisition on October 21 but declined to signal any change in the carrier’s position.
JetBlue is not yet out of cash, and its valuable airport operations, loyalty program and customer base could attract potential buyers. However, heavy debt, continuing losses and expensive financing obligations leave the airline with limited room for setbacks as it works toward sustainable profitability.
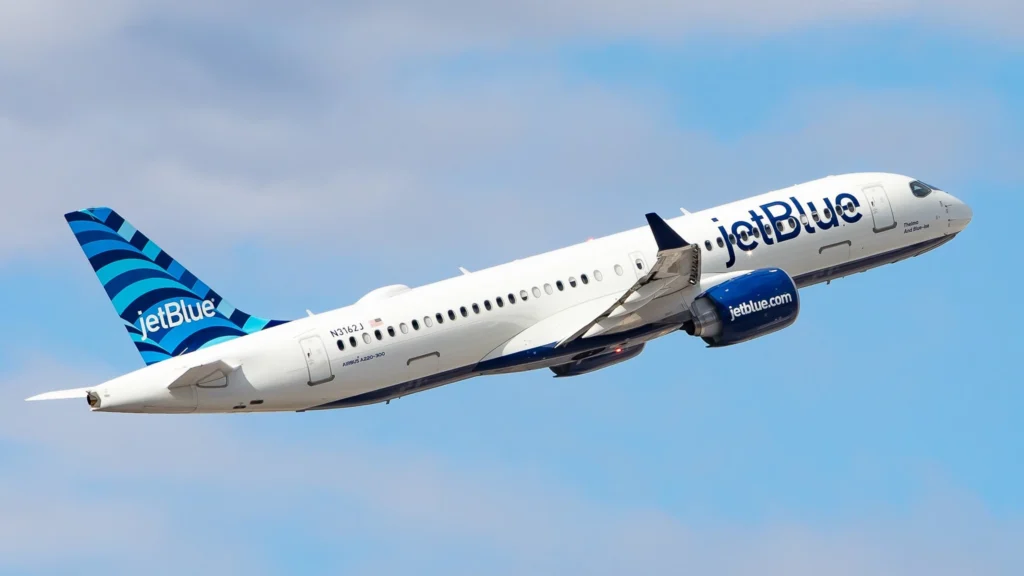
JetBlue Bankruptcy Risk
JetBlue reported approximately $2.2 billion in unrestricted cash, cash equivalents and investment securities at the end of June 2026, alongside an undrawn $600 million credit facility.
Its second-quarter filing also showed around $8.5 billion in debt and finance lease obligations, excluding operating lease liabilities.
The airline lost $566 million during the first half of 2026. Although its cash reserves provide a financial cushion, losses and interest payments could steadily reduce that protection if operating performance fails to improve.
JetBlue’s scheduled debt repayments include $236 million for the remainder of 2026, $478 million in 2027 and $582 million in 2028.
Payments rise sharply to approximately $1.84 billion in 2029, making access to refinancing and additional capital increasingly important.
The share price alone cannot establish whether bankruptcy is imminent. Research into corporate failure has found that stock-price declines can help identify financial distress when considered alongside leverage, profitability, volatility, and available cash. JetBlue’s low valuation is therefore a warning sign, not a definitive prediction of its future.
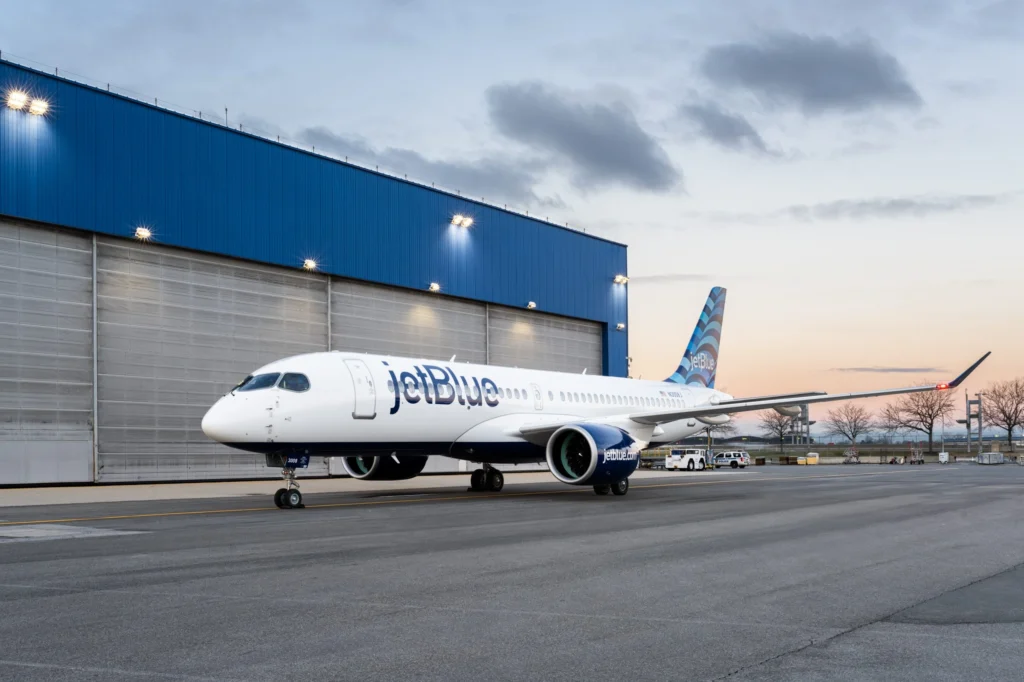
JetBlue’s Turnaround Faces Pressure
JetBlue has been working to increase revenue from existing customers through premium seating, airport lounges, credit-card partnerships and its TrueBlue loyalty program.
Its second-quarter results showed revenue growth of 14.5%, while revenue per available seat mile at Fort Lauderdale increased 11%, despite a substantial capacity expansion.
However, improved revenue has not yet translated into consistent profitability. JetBlue recorded a $141 million operating loss in the second quarter, while its 2026 outlook anticipated approximately $590 million in interest expense.
The airline has also sought to raise money against assets, including aircraft and its loyalty program. Its TrueBlue-backed bonds have come under pressure, highlighting concerns about how lenders value the collateral and what financing might cost.
JetBlue has targeted positive free cash flow around late 2027 or 2028, but that goal depends on successful execution and favorable operating conditions. Higher fuel prices, weak demand or delays in improving costs could make the turnaround more difficult.
The airline is scheduled to report its third-quarter results on October 27. The update should provide a clearer view of its latest cash position, losses and progress toward its financial targets.
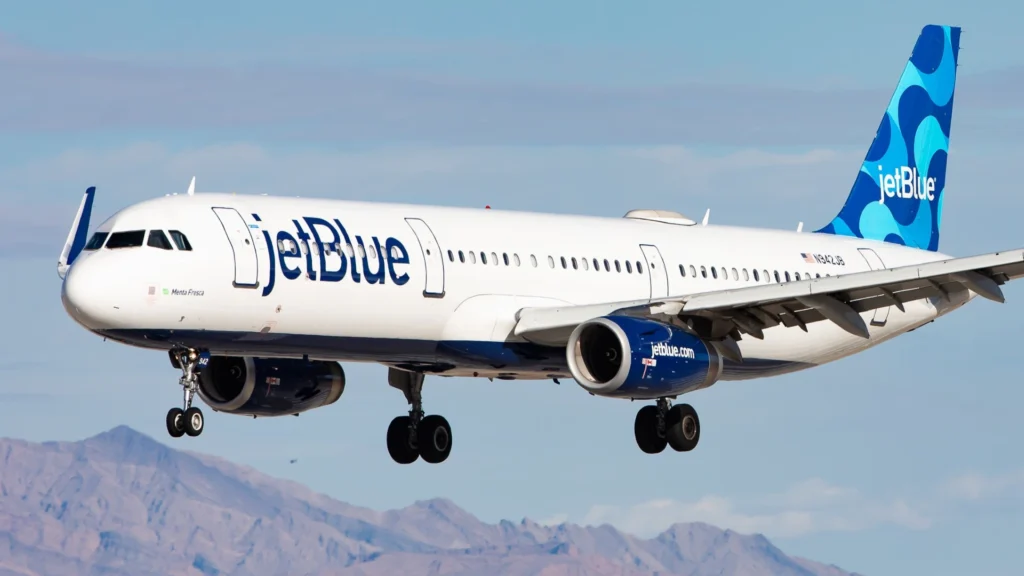
Will United Buy JetBlue?
United Airlines remains a potential source of speculation because JetBlue has valuable assets in competitive markets, including New York airport slots, Boston operations, and a significant presence in Fort Lauderdale. Its loyalty program could also hold strategic value for another carrier.
However, acquiring JetBlue would mean assessing not only those assets but also its substantial debt and financing commitments.
A buyer would need to determine whether the network and customer benefits justify the cost and complexity of a transaction.
During United’s October 21 earnings call, CEO Scott Kirby was asked whether the airline could be a solution for JetBlue as it considers its financial future. Kirby said he had nothing new to add and emphasized United’s focus on its own business.
United had recently increased its liquidity, but its executives said the move was not intended to finance an acquisition. There is no confirmed deal or public commitment from United to buy JetBlue, View from the Wing flagged.
For now, JetBlue’s future depends more immediately on whether it can slow cash burn, refinance upcoming obligations and make its turnaround profitable.
Bankruptcy remains a genuine risk if financing becomes harder to obtain, but the available figures do not establish that a filing is imminent.
United could still be part of a future industry consolidation, but investors should not treat a takeover as a guaranteed safety net.
Stay tuned with us. Further, follow us on social media for the latest updates.
Join us on Telegram Group for the Latest Aviation Updates. Subsequently, follow us on Google News
